Qatar Divorce Rate 12th Highest in the World
Today’s story in The Peninsula examines the increasing number of divorces this year, in relation to the number of marriages.
Not a single expert quoted mentions that perhaps many of these marriages were bad alliances in the first place. One expert continually mentions the problem being women having greater access to divorce.
It is no surprise that women who have access to divorce get out of bad marriages.
She is supposed to stay with a man addicted to pornography?
With a man who cannot complete the sexual act?
With a man with a drug problem?
With a man who is openly gay, and she is to provide cover?
With a man who has a fatal sexually transmitted disease which he neglected to disclose?
With a man who is still emotionally attached to his long-time girlfriend and was forced to marry another woman?
With a man who hits her?
With a man who ignores her and goes off with his friends all the time in preference to spending time with her? (Yes, expectations for marriage are higher now than they used to be. Times change. Expectatons change.)
(These are all stories told to me by local women about failed marriages.)
I’m not a big fan of divorce. I think marriage is serious business, and a lot of hard work. And I strongly believe that women need to have the exact same access to divorce that men have. I don’t see any of the experts citing male behavior as a possible cause of this divorce rate.
Divorce rate to reach new high this year
Web posted at: 12/30/2009 5:38:55
Source ::: The Peninsula / BY SATISH KANADY
DOHA: Qatar’s divorce rate is steadily going up. Crossing last year’s figure of 939 divorces, a total of 982 couples split in the country during the first 11 months of this year.
Going by the latest data released by the Qatar Statistics Authority (QSA), more than 80 divorces take place every month in the country. The 2009 figure is expected to cross the 1,000 mark once the figures for December come in.
According to the QSA, of the 982 divorce cases this year, 655 involved Qatari women. The number of non-Qatari women who split with their spouse during the period was 327.
The months of April, May and June witnessed a large number of divorces. While 127 women got divorced during the month of May, 107 and 101 women got divorced in June and April, respectively.
It may be noted that a recent international study identified Qatar as the country with the 12th highest divorce rate in the world. The country has 0.97 divorces per thousand people, it said.
The total number of divorces in the country in 1999 was 496. However, the number has grown steadily over the past decade and touched 997 in 2007, with a total of 721 Qataris and 276 non-Qataris getting estranged. Though the rate went down in 2008 (939), this year’s figures are expected to break the 2007 record.
The QSA’s figures are disturbing against the backdrop of the fact that the total number of marriages held this year in Qatar until November 2009 was 2,917, against which the number of divorces was 982.
Against the 266 marriages that took place last month, 90 couples got divorced. Of them, 57 included Qatari women. In the month of May, which witnessed the largest number of divorces — 127 — the number of marriages was 323.
Opinions are divided among Qatari social scientists on the data revealed by the QSA. While a section of them sees the divorces as a direct consequence of Qatar’s “culture shock”, others say QSA’s methodology in collecting the data is not foolproof and the figures do not seem realistic.
“The data collected from the courts need not necessarily reflect the exact divorce rate in Qatar. For, there are a large number of cases where the couples re-join after obtaining a divorce from the court”, said a Qatari woman scholar who is doing research on Qatar’s broken families and divorces.
However, Moza Al Malki, a prominent Qatari psychologist, said: “Qatari women’s exposure to the changing world and their growing self-reliant nature are the prime reasons for this social problem.”
Al Kula, a system that encourages women to approach a court if they are not comfortable with their partner, is also contributing to the growing number of divorces, she added.
Stieg Larsson and The Girl With the Dragon Tattoo
I needed some escape time, so I started The Girl With the Dragon Tattoo, a mystery by Stieg Larsson, set in Sweden. I love these detective stories set in other countries; I can learn something as I pass the time reading an exciting mystery. And part of my heritage is Swedish, so I thought this should really be fun.
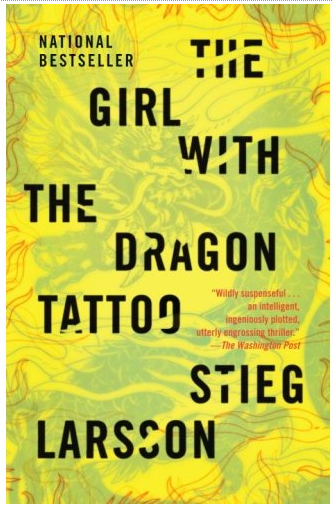
It wasn’t, at least not at the beginning. At the beginning, I didn’t like any of the characters, and they were always eating sandwiches that sounded awful, like liverwurst and egg. I felt like the characters didn’t have any moral center, like they drifted from day to day without neither conscience nor a plan. The main character, Mikael Blomkvist, is about to go to prison for libel; he printed a story about a major industrialist which turned out to be false, and he protected his source. We don’t really know the whole story, not until the end, which makes it hard to evoke a lot of sympathy for Blomkvist.
He is contacted by another industrialist, and asked to solve a mystery, if possible, about the disappearance, 40 years ago, of his niece, Harriet Vanger. Blomkvist would investigate under the cover of writing an autobiography of his employer and his family. There are members of the family who object. In many ways, it isn’t a very nice family.
Blomkvist gets an assistant, a deeply troubled and flawed young woman, Lisbeth Salander, with a gift for investigation. There is a lot of violence, sexual violence, and mutilation of animals. One of the points I credit Larsson with making is the amount of violence against women in Sweden, which goes on under a seemingly civilized veneer. The truth, as I see it, is that there is violence against women in every society; in some it is better documented than in others. In some, it is better punished that others. It exists in all societies, in all countries.
Another think I ended up liking about the book was that the main character, Blomkvist, who writes financial analysis, takes the press to task for printing what passes for financial news without critically reading and evaluating, which he feels is a responsibility of the press. At one point, as people quail with fear that the stock exchange will drop dramatically, he is interviewed and explains that the stock market is based on perceptions, while the Swedish economy is based on production and services; that while the markets may fail, the economy can still be going strong.
Slowly, the book tightens up. Actually, by the end, I was hooked. The only question in my mind is – did I like it enough to read another?
The book is available, new, from Amazon.com at $6.00 plus shipping.
Three Market Trends for 2010
From The Peninsula Business Section
Three market trends to watch for in ’10
Web posted at: 12/27/2009 11:51:49
Source ::: LAT-WP
Washington: In case you missed it, Treasury Secretary Timothy F Geithner this week promised America that there won’t be another financial crisis in 2010.
“We’re not going to have a second wave of financial crisis,” Geithner said in an interview with National Public Radio. “We’ll do what is necessary to prevent that. We cannot afford to let the country live again with a risk that we’re going to have another series of events like we had last year.”
Well, there it is. And you wonder why the stock market is at 14-month highs? Anyone who has deep-seated doubts about the financial system’s health may view Geithner’s explicit guarantee as a sign of dangerous government hubris, or simple naivete.
But his promise does address what is for some investors the pre-eminent question about 2010: Can the world avoid another calamity on the scale of what fueled the markets’ meltdown from September 2008 to March 2009?
To put it another way: Your financial planning for the new year would be a lot easier if you knew that the chance of another collapse was remote even if markets were likely to be volatile.
The strongest evidence against a second collapse is that the credit crisis has eased dramatically. That may not be evident in banks’ lending. But by many key barometers, including new issuance of corporate bonds and the rates banks charge each other for short-term loans, credit has begun to flow again worldwide.
If we assume that Geithner is right about the absence of another mega-crisis in 2010, I think there are three important financial trends that either got under way or accelerated in 2009 that also will be critical for investors and savers in the new year:
The Great Deleveraging rolls on. Many Americans piled on excessive debts in the 1980s, 1990s and first half of this decade. On that much, everyone agrees. Now, that total household debt load of $14 trillion is being worked down — voluntarily, as people pay off credit cards, for example, or involuntarily, as banks force foreclosures. Consumer credit excluding mortgages fell for a ninth straight month in October, a record stretch of declines, according to Federal Reserve data.
But debt reduction has a “long, long way to go,” says Ian Shepherdson, chief US economist at High Frequency Economics in Valhalla, New York. The question is whether it can proceed without tipping the economy back into recession.
One ticking time bomb: a jump in 2010 in the number of homeowners with so-called option ARM loans who will see their loan rates reset at higher levels.
An obvious implication of consumers’ need to reduce debt is that people will save more and consume less than before. That will be a continuing drag on the economic recovery. I know we’ve all heard that a million times, but that doesn’t make it less true.
The upshot: no imminent rate relief for savers who now are lucky to earn 1 percent or 2 percent on their cash.
Corporate earnings keep improving. Expectations of a profit recovery helped stoke the stock market’s turnaround in March. Wall Street has been pleasantly surprised since then.
Starting with the current quarter, earnings are forecast to begin rising, albeit from extremely depressed year-earlier levels.
Sales have edged up for many companies this year as the global economy has begun to rebound. But a big part of the profit-recovery story has stemmed from companies’ slashing of their payrolls, driving the US unemployment rate above 10 percent for the first time since 1982.
Many investors keep looking for a middle ground on risk-taking. That means cash probably will keep pouring into bonds — at least until some people discover, to their surprise, that it’s possible to lose money in fixed-income securities, too.
Small investors usually are prone to chasing hot stock markets. Not this year. Even as the US stock market has continued to rally Americans have shunned domestic stock mutual funds. Each week since late August more cash has been pulled from them than has flowed in via new purchases, according to the Investment Company Institute’s data.
Mixed Forecast
Interesting article from today’s Peninsula Business Section on rising mortgage trends in the United States. The views are so mixed; is the economy recovering? Are there going to be buyers for all those houses on the market? Will they find a way to forestall the next round of foreclosures as ARMs come due and new rates kick in?
US mortgages on upward trend
Web posted at: 12/27/2009 11:52:57
Source ::: LAT-WP
WASHINGTON: After hitting an all-time low in early December, the average rate on a 30-year, fixed-rate mortgage rose to 5.05 percent this week and could climb to 6 percent by the end of 2010, if not sooner, according to giant mortgage financier Freddie Mac.
The results are noteworthy because rates have not topped 5 percent since the last week of October, when they reached 5.03 percent, based on the results of this closely watched survey, which polls lenders during the first three days of every week.
Many firms regularly track interest rates and come up with slightly different numbers because they survey different lenders at different times of the day or week. But several have reported the upward trend in recent weeks. They attribute it in part to the effects of the holiday season, when demand for buying and refinancing homes dies down and financial markets coast through the end of the year.
“However, this is also a glimpse of what we’re going to see in 2010,” said Greg McBride, a senior financial analyst at Bankrate.com, a personal finance Web site.
The key catalyst for interest rates going forward will be the end of a Federal Reserve program that buys a sizable chunk of mortgage-backed securities issued by firms such as Fannie Mae and Freddie Mac. That program succeeded in immediately pushing mortgage rates well below the 6 percent mark when it was announced last year.
But the Fed has committed to winding down the program by March. The central bank is betting that by gradually tapering its purchases, private buyers of mortgage-backed securities, who have largely been absent from the market, will return and rates won’t rise much.
But Amy Crews Cutts, deputy chief economist at Freddie Mac, said interest rates are bound to rise to six percent by the end of 2010 because private buyers will demand a higher rate of return on the securities than the Fed did. Lenders may have to raise the rates they charge to consumers in order to make that happen.
“Extraordinary resources have been put into keeping the rates down and supporting the mortgage markets and it’s hard to imagine that the rates can go much lower than they are,” Crews Cutts said. “Anything we get at or below five percent is a gift at this point.”
This week’s Freddie Mac survey found that the 5.05 percent average on 30-year fixed-rate loans (with an average 0.7 point) was up from 4.94 percent the previous week but down from 5.14 percent at the same time last year. The all-time weekly low since the firm started tracking the numbers in 1971 was in the first week of December, when rates fell to 4.71 percent.
Many borrowers have not been able to secure the best rates because they lack the stellar credit scores and hefty down payments that many lenders now demand. Some who have tried to refinance have not been able to qualify because their home prices have plummeted to the point where they now owe more on their mortgages than their homes are worth.
But anyone who can secure a loan should not wait much longer, especially if they are looking to refinance, McBride said. Homeowners are more sensitive to interest rates when they refinance than when they buy a home. “The difference between 5 percent and 5.5 percent could mean the difference between refinancing or not,” he said.
But the interest rate is less critical to people who want to buy a home, McBride said. In that case, price and affordability should trump interest rates.
Me and the FBI
Got this e-mail today from the FBI (yeh, right.)
Federal Bureau of Investigation (FBI)
Anti-Terrorist And Monitory Crime Division.
Federal Bureau Of Investigation.
J.Edgar.Hoover Building Washington Dc
http://www.fbi.gov/libref/directors/directmain.htm
Attn: Beneficiary,
This is to Officially inform you that it has come to our notice and we have
thoroughly Investigated with the help of our Intelligence Monitoring Network
System that you are having an illegal Transaction with Impostors claiming to be
Prof. Charles C. Soludo of the Central Bank Of Nigeria, Mr. Patrick Aziza, Mr
Frank Nweke, Dr. Philip Mogan, none officials of Oceanic Bank, Zenith Banks,
Barr. Derrick Smith, kelvin Young of HSBC, Ben of FedEx, Ibrahim Sule,Larry
Christopher, Dr. Usman Shamsuddeen, Dr. Philip Mogan, Paul Adim, Puppy Scammers are impostors claiming to be the Federal Bureau Of Investigation. During our Investigation, we noticed that the reason why you have not received your payment is because you have not fulfilled your Financial Obligation given to you in
respect of your Contract/Inheritance Payment.
Therefore, we have contacted the Federal Ministry Of Finance on your behalf and
they have brought a solution to your problem by coordinating your payment in
total USD$11,000.000.00 in an ATM CARD which you can use to withdraw money from any ATM MACHINE CENTER anywhere in the world with a maximum of $4000 to $5000 United States Dollars daily. You now have the lawful right to claim your fund in an ATM CARD.
Since the Federal Bureau of Investigation is involved in this transaction, you
have to be rest assured for this is 100% risk free it is our duty to protect the
American Citizens. All I want you to do is to contact the ATM CARD CENTER via
email for their requirements to proceed and procure your Approval Slip on your
behalf which will cost you $110.00 only and note that your Approval Slip which
contains details of the agent who will process your transaction.
CONTACT INFORMATION
NAME: Mr. Kelvin Williams
EMAIL: williamskelvin22@yahoo.cn
Telephone: +2348191213677
Do contact Mr Mr. Kelvin Williams of the ATM PAYMENT CENTER with your details:
FULL NAME:
HOME ADDRESS:
TELL:
CELL:
CURRENT OCCUPATION:
BANK NAME:
AGE:
So your files would be updated after which he will send the payment
information’s which you’ll use in making payment of $110.00 via Western Union
Money Transfer or Money Gram Transfer for the procurement of your Approval Slip
after which the delivery of your ATM CARD will be effected to your designated
home address without any further delay.We order you get back to this office
after you have contacted the ATM SWIFT CARD CENTER and we do await your response so we can move on with our Investigation and make sure your ATM SWIFT CARD gets to you.
Thanks and hope to read from you soon.
ROBERT S. MUELLER, III
DIRECTOR, FEDERAL BUREAU OF INVESTIGATION
UNITED STATES DEPARTMENT OF JUSTICE
WASHINGTON, D.C. 20535
http://www.fbi.gov/libref/directors/directmain.htm
Note: Do disregard any email you get from any impostors or offices claiming to
be in possession of your ATM CARD, you are hereby advice only to be in contact
with Mr. Kelvin Williams of the ATM CARD CENTER who is the rightful person to
deal with in regards to your ATM CARD PAYMENT and forward any emails you get
from impostors to this office so we could act upon and commence investigation.
LLLOOOOOLLLLLL!
Bad grammar, bad word choices, gives you away every time, scammers!
Defense: It’s The Cops Fault; He Was Chasing Me!
Court asks motorcycle rider to pay blood money
Web posted at: 12/19/2009 2:30:29
Source ::: THE PENINSULA
DOHA: A young man who rode a motorcycle and killed a pedestrian in a bizarre crash has been asked by the court to pay QR200,000 as blood money to the family of the deceased.
The court fined the convict QR10,000 for violating traffic law. But how the man was caught by the law-enforcement agencies is quite interesting.
It so happened that the Police Patrol saw two men riding motorbikes with tremendous speed. They gave the duo a chase but in vain. They vanished in think air. But soon the police was informed that a pedestrian was hit by a speeding motorbike.
When a police party reached the spot of the crash it saw a motorbike lying near the body of the victim.
The cops were quick to realize that this was one of the two motorbikes they had given a chase sometime ago.
With help from its registration plate they zeroed in on the culprit and referred the matter to the court after investigation.
The defense lawyer argued in the court that the crash occurred because they motorbike was chased by the cops. The court, however, did not buy the argument and convicted the man.
QR 200,000 sounds like a fortune, but it is $55,000 for taking a man’s life. For a young man who was running from the cops and then tries to claim their chasing him as a defense! This case sounds like a perfect opportunity to give a community service penalty in addition to the blood money; expose this young man to the consequences of motorcycle accidents, and accident victims, allow him to see with his own eyes, and serve, the victims. It could change his life, and change his callous attitude.
Doha unscathed by downturn: PM
He’s the prime minister. I guess I am wrong. I thought I saw a lot of constructions at a stand still. It looked to me like the population of laborers has dropped. People are slipping away, expat management level workers, being let go, heading home. There are some empty units on our highly-sought after compound. Few people at Villagio are carrying shopping bags; most of the bags leaving City Center appear to be Carrefour groceries or Home Center: on sale. Rents are dropping.
It looks to me like something is dragging on the Qatar economy, it looks to me like there may be some empty seats on flights in and out. But I must be wrong.
You can read the entire article by clicking on the blue type below, which will take you to the article in The Peninsula.
Doha unscathed by downturn: PM
Web posted at: 12/8/2009 2:8:12
Source ::: The Peninsula
By Nasser al Harthy
DOHA: The global economic downturn has not affected any of Qatar’s projects, Prime Minister and Foreign Minister, H E Sheikh Hamad bin Jassem bin Jabor Al Thani, said here yesterday.
Addressing the opening of the fourth edition of the International Petroleum Technology Conference (IPTC), Sheikh Hamad Bin Jassem said: “We, in Qatar have overcome the consequences of the crisis with minimum damages and that the crisis has not affected any of our projects being implemented, whether in the oil sector, gas sector or development and infrastructure projects undertaken by other state sectors.”
“We are moving forward with full determination to implement all our ambitious plans which focus on sustainable development in which oil, gas and industry play a basic role and constitute one of its strong pillars,” he added.
The Prime Minister noted that the world economy passed through a difficult period of recession last year leading to a sharp drop in oil and gas consumption in world markets and energy prices in general.
“Why Bank of America Fired Me”
When AdventureMan and I were young, we visited a financial advisor. He gave us some good advice. He also put us in some very bad funds. Well, bad for us – he made a lot of money on up-front charges. We learned a lot from him; we also learned a whole lot more from dealing with him about being responsible for our own money management.
One thing we learned: No one cares about you and growing/investing your money more than you do. Others may care about separating you from your money. Any time a financial institution uses the words “for your convenience” read the fine print. Always, read the customer agreements.
This very brave girl, Jackie Ramos, a former Bank of America “customer assistant” tells us what her “services” really meant. She got fired for taking a stand, but she makes a great video outlining BofA credit card collection policies.
1 in 4 US Mortgages “Under Water”
1 in 4 mortgages ‘underwater’
Report shows 10.7 million borrowers are stuck with homes that are worth less than the mortgages they owe.
By Julianne Pepitone, CNNMoney.com staff reporter
Last Updated: November 24, 2009: 12:19 PM ET
Foreclosure plague: It’s spreading
NEW YORK (CNNMoney.com) — In a sign that more foreclosures could be on the horizon, 23% of people with mortgages owe more than their home is worth, according to a report released Tuesday.
Almost 10.7 million U.S. mortgages were “underwater” as of September, said research firm First American CoreLogic.
Another 2.3 million homeowners are within 5% of negative territory, the report said. The two figures combined comprise almost 28% of all residential properties with mortgages.
Negative equity, also called an “underwater” or “upside down” mortgage, has become more common as home values plummet. The report is closely watched because borrowers who are underwater are more likely to be foreclosed.
Would you walk away from your house?
Foreclosures have been rampant for some time, but lately the tide of decay had seemed to be slowing — so Tuesday’s report could dent optimism for the housing market over the next few months.
On the other hand, the trend that turned so many mortgages upside-down — falling home prices — has reversed the past six months. The S&P/Case-Shiller HomePrice Index has reported two consecutive quarters of increasing prices.
If home prices continue to go up or, at least stabilize, fewer mortgage borrowers will find themselves underwater in the coming months.
CoreLogic changed its methodology for the third quarter — now it accounts for payments that reduce principal, and it no longer assumes home equity credit lines have been maxed out. Using the old method, 33.8% of borrowers would have been underwater in the third quarter compared with 32.2% in the previous quarter, according to a CoreLogic spokeswoman.
State totals: The majority of underwater mortgages are heavily concentrated in five states that have particularly suffered from the housing bust: Nevada, at 65%; Arizona, at 48%; Florida, at 45%; Michigan, at 37%; and California, at 35%.
These five states have been especially beleaguered because of a high rate of prime loans that went bad. Many of those loans were option-adjustable rate mortgages, in which borrowers could choose to make minimum payments that were so low they did not even offset the interest being accumulated.
When that accumulated debt reaches a certain point — usually 10% to 25% more than the original principal — the option-ARMs loans are recast into fixed-rate mortgages. When that happens, many borrowers cannot afford the new payments.
Recent Comments
intlxpatr on Shampoo Ginger tigerbutterya0c5ff1d… on Shampoo Ginger intlxpatr on British Soldier Kidnapped, Esc… John on British Soldier Kidnapped, Esc… intlxpatr on British Soldier Kidnapped, Esc… Wikipedia Donate Button

Amazina


Early Voting in Florida


